Robinhood Banking
RobinhoodFinanceVerified
- 1.54K Reviews
- 4.9
- Downloads
- 100,000+
- Price
- Free
Screenshots
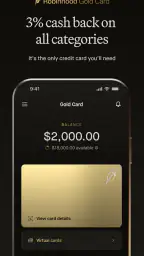
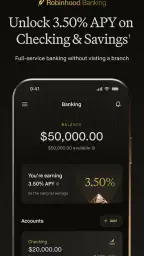
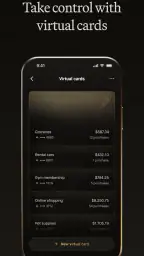
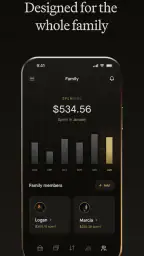
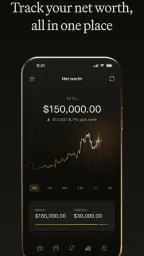
 Analysis by Appwesome
My first impression of Robinhood Banking is that it asks very little of a new user: the layout feels approachable, and the main idea—bringing banking and investing into one app—is easy to grasp. That quick appeal matters, but it is not enough to earn permanent space on my phone. What matters more is whether the app fits a sensible routine after the novelty of watching an account move wears off.
Who gets the most from a simple starting point
I can see this finance app working well for someone who is curious about investing but does not want to begin with a dense trading terminal. Robinhood, the developer, has made its name familiar to people who want a direct route to markets, and the app’s simple presentation can lower the barrier to exploring that world. It is also a natural candidate for someone who already wants to keep everyday money and investing activity close together rather than switching between several apps.
That convenience is most useful when it supports a clear purpose. If I were checking a balance, reviewing a holding, and then deciding whether a small planned contribution still fit my budget, having those tasks in one place could reduce friction. I would still keep a separate household budget or financial plan if I needed one; a brokerage-centered interface is not automatically a complete picture of someone’s finances.
How I would fit it into an ordinary week
Imagine I have a quiet moment after payday and want to check where my money stands before setting aside an amount for investing. I could use the app to look over my account and make a deliberate decision rather than reacting to a sudden market move. The useful habit is the review itself: decide what the money is for, check that the choice matches that purpose, and then close the app instead of repeatedly refreshing prices.
A less obvious but helpful approach is to separate “checking” from “trading.” I would choose a regular time to review my finances and avoid treating every notification or price change as a reason to act. That distinction can matter especially for a beginner, because an easy-to-use trading screen may make frequent activity feel effortless even when doing nothing is the better decision. The app can make an action quick; it cannot make the action wise.
Where it sits beside other finance apps
Compared with a traditional bank app, Robinhood’s appeal is its investment-oriented focus and the possibility of managing cash alongside trading. A bank app may be a better home for people who mainly need established payment routines, detailed account services, or a broader view of their everyday banking. Compared with a more research-heavy brokerage, Robinhood’s cleaner experience may feel less intimidating, but people who rely on deeper analysis and specialist tools may prefer a platform built around those needs.
That trade-off is worth thinking through before moving your routine. An all-in-one feel can be convenient, but it can also blur the line between cash meant for bills and money exposed to investment risk. I would keep a clear mental—or written—separation between those purposes and verify the account details that matter to me before relying on any app for regular financial tasks.
Other Stories to Read




What to check before making it a habit
Because this is a finance app, I would take a few minutes to review the account setup, security options, and the way transfers are presented before making it part of my weekly routine. I would also read the terms attached to any feature I plan to use, rather than assuming that familiar labels mean the same thing they do at my bank. That is a more useful first session than immediately placing a trade.
It is reasonable to ask whether the app costs anything to try, whether it is suitable for younger users, and whether it runs on an older device. Robinhood Banking is free, is rated for Everyone, and lists Android 7.0 as its minimum operating system. The app was released on March 19, 2024, and version 2.3.1 is the current version. Those details make it easier to judge basic access, though they do not replace checking whether a particular financial feature is available and appropriate for your circumstances.
The app has an average rating of 4.9 from around 15,000 ratings, with about 1,500 written reviews, and has passed 100,000 installs. I treat those figures as a sign that many people have tried it, not as proof that it will suit my habits. A popular app can still be the wrong tool if I need a different kind of support or prefer to keep investing and banking entirely separate.
When I would choose something else
I would look elsewhere if my priority were comprehensive financial planning, extensive portfolio research, or the reassurance of handling all routine banking through the institution I already use. I would also be cautious if market movement tends to make me anxious or encourages impulsive decisions. In that case, a simpler savings-focused routine—or an investment service with a less trading-centered experience—may better support the behavior I want.
On the other hand, a curious beginner who values an uncluttered entry point may find Robinhood easier to approach than a platform designed for active professionals. I would still start with small, intentional steps and learn how each account function works before making it the center of my financial life. The important question is not simply whether the app has useful tools, but whether its style helps me make calmer, more consistent choices.
Over a month, the app’s recurring value would come from a few practical jobs: checking balances, reviewing investments, and handling the cash-related tasks I actually use. If I only open it to watch prices, its novelty is likely to fade—or turn into a distraction. If it supports a planned review and saves me from unnecessary app-hopping, it has a better chance of earning a lasting place.
Keeping the routine useful, not noisy
My maintenance rule would be simple: make the app serve a routine instead of letting the routine serve the app. I would decide in advance how often I need to check in, keep money for near-term expenses distinct from investment decisions, and revisit my settings when my circumstances change. Those habits do more for long-term usefulness than opening the app every day without a reason.
There is also a real attention trade-off in combining market information with personal money management. A quick balance check can turn into browsing prices, and that can make ordinary financial housekeeping feel urgent. I would avoid using a short idle moment as an invitation to trade. If I need a detailed comparison or a longer research session, I would use tools that give me the depth I need rather than expecting a streamlined phone interface to answer every question.
One practical test is to ask, after a few weeks, which repeated task the app has made easier. If the answer is clear—perhaps a regular account review or a convenient way to keep track of investing activity—that is a good reason to keep it. If I cannot name a recurring job and mostly open it out of habit, I would reconsider whether it belongs on my home screen. Convenience is valuable when it removes friction from a sound plan, not when it creates more reasons to check.
Another question is whether it can replace a bank or a dedicated brokerage. I would not assume that it should. The better choice depends on what I need most: everyday banking breadth, research and analysis, or a simpler place to approach trading and cash management. I would compare the actual account functions and terms I plan to use, then keep any existing service that still handles an important task better.
For anyone wondering how to begin without turning the app into a source of pressure, I would start by exploring the interface and reading the details for each feature before moving money or placing a trade. Then I would set one specific purpose for using it, such as a scheduled review. That small boundary helps preserve the main advantage—easy access—without mistaking access for a recommendation to act.
Getting Started with Robinhood Banking
Let’s dive into the world of Robinhood Banking, an app that’s been creating quite the buzz in the financial sector. If you’ve been looking for a way to manage your investments and personal finances all in one place, you might have stumbled across this app. I’ve taken it for a spin, and here’s the lowdown on what it offers, and whether it lives up to the hype.
First off, downloading the Robinhood Banking app is a breeze. It’s available on both Android and iOS, so you’re covered no matter what platform you’re loyal to. The installation process is straightforward, and within minutes, I was ready to explore its features. The app greets you with a sleek, minimalistic design that’s easy on the eyes and incredibly intuitive. Even if you’re not a tech-savvy person, you’ll find navigating through the app a piece of cake.
Features That Stand Out
The app offers a myriad of features aimed at making financial management simpler and more accessible. Here’s a quick rundown of what caught my attention:
- Commission-Free Trading: One of the biggest draws of Robinhood is its commission-free trading. You can trade stocks, ETFs, and options without worrying about those pesky fees eating into your profits.
- Real-Time Market Data: Stay informed with real-time market data. Whether you’re a seasoned trader or a newbie, having access to up-to-date information is crucial for making informed decisions.
- Cash Management: The app also offers cash management features, allowing you to earn interest on uninvested cash and use a debit card linked to your account for everyday purchases.
These features make Robinhood Banking not just a trading platform, but a comprehensive financial tool.
Ease of Use and User Experience
One thing I absolutely love about this app is its user-friendly interface. The design is clean, and the navigation is smooth. Whether you’re checking your portfolio, making a trade, or transferring funds, everything is just a tap away. Plus, the app includes educational resources to help you make better investing decisions, which is a huge plus if you're just starting out.
Another noteworthy feature is the app’s security. In today’s digital age, securing financial data is paramount, and Robinhood does a commendable job here. It employs advanced security measures to protect your personal information and financial details.
Is Robinhood Banking Right for You?
Now, who exactly is Robinhood Banking for? If you’re someone looking for a simple, cost-effective way to trade and manage your finances, this app could be a great fit. Its commission-free model is particularly attractive for those who trade frequently. However, if you’re looking for more advanced trading tools or prefer a more hands-on approach to investing, you might find the app a bit limiting.
Moreover, the app's focus on simplicity may not satisfy traders who require in-depth analysis tools and extensive market research. But for the average user or beginner investor, the ease of access and straightforward interface are huge advantages.
Final Thoughts
Wrapping it up, Robinhood Banking offers a compelling package for anyone interested in trading and managing personal finances in one place. Its user-friendly design, coupled with the lack of trading commissions, makes it a standout choice for many. However, it might not cater to those in need of more robust trading features. If you’re curious, it’s definitely worth downloading and exploring yourself. After all, in the world of finance, having the right tools at your fingertips can make all the difference.
So, what are you waiting for? Give it a try and see if it fits your financial goals. You might just find it’s the financial companion you’ve been looking for!
Highlights
- User-friendly interface for easy navigation.
- Commission-free trades save money.
- Real-time market data streaming.
- Instant access to deposited funds.
- Fractional shares available for investment.
Limitations
- Limited research and analysis tools.
- No retirement account options.
- Customer support can be slow.
- Only available in the U.S.
- No mutual fund investments.
Frequently Asked Questions
01What is Robinhood Banking and how does it work?
Robinhood Banking is a financial app that offers commission-free stock trading and banking services. It allows users to invest in stocks, ETFs, and cryptocurrencies directly from their mobile devices. The app provides tools for portfolio management and market insights, making it accessible for both beginners and experienced traders. Users can also access cash management services, including a debit card.
02Is Robinhood Banking safe to use?
Yes, Robinhood Banking implements several security measures to protect user information and funds. It uses encryption, two-factor authentication, and biometric login options. Additionally, Robinhood is a member of the Financial Industry Regulatory Authority (FINRA) and the Securities Investor Protection Corporation (SIPC), which provides some level of investment protection. However, it's always advisable to understand the risks involved in investing.
03What are the main features of Robinhood Banking?
Robinhood Banking offers commission-free trades, fractional shares, and access to a wide range of investment options like stocks, ETFs, and cryptocurrencies. It also provides cash management features, including a high-interest savings account and a MasterCard debit card. The app includes market data, news, and educational resources to help users make informed investment decisions.
04Are there any fees associated with Robinhood Banking?
While Robinhood Banking is known for its commission-free trades, there may be other fees involved, such as regulatory fees on certain transactions and fees for transferring funds to external accounts. Additionally, premium services like Robinhood Gold, which offers margin trading and additional research tools, come with a subscription fee. Users should review all potential fees before using the app.
05Can I use Robinhood Banking internationally?
Currently, Robinhood Banking is only available to users in the United States. To use the app, you need to be a U.S. resident with a valid Social Security Number. The company has plans to expand internationally in the future, but as of now, it's limited to the U.S. market. International users should keep an eye on announcements for availability in their regions.


